Understanding project cost is fundamental to successful construction and engineering project management. Project cost refers to the total expenditure required to plan, design, construct, manage, and complete a project successfully. A comprehensive cost assessment enables clients, contractors, consultants, and developers to prepare realistic budgets, allocate resources efficiently, control expenditure, manage risks, and make informed financial decisions.
Direct Costs: Direct costs are expenses that can be directly linked to specific construction activities and are usually a major part of the project budget.
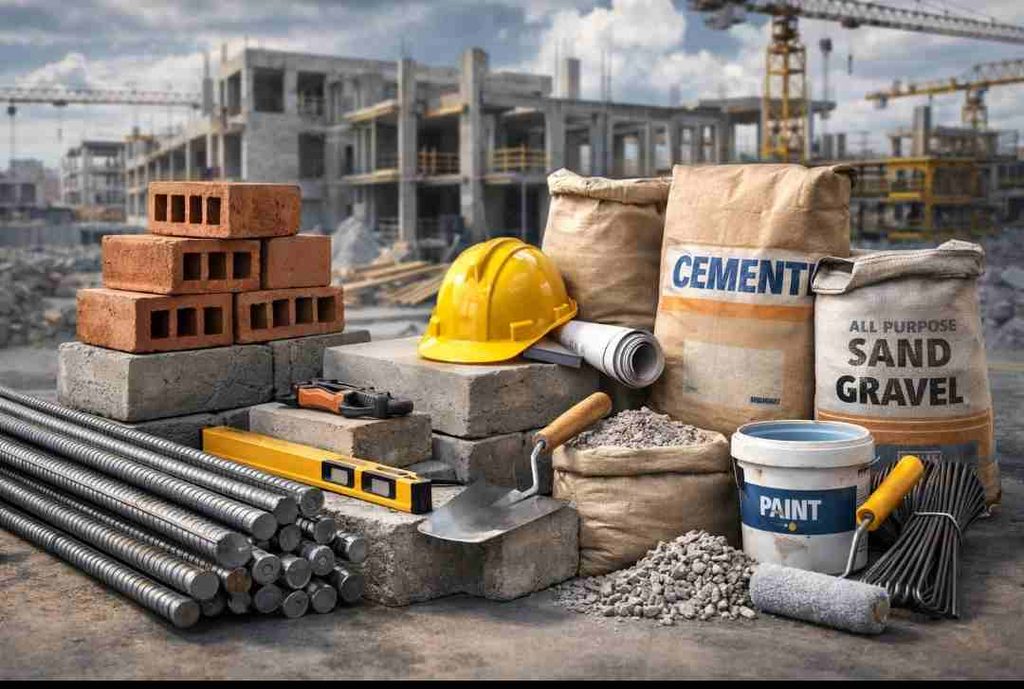
Materials include cement, sand, reinforcement steel, blocks, timber, roofing materials, electrical fittings, plumbing fixtures, paints, and finishes. Their costs are affected by market prices, transportation, availability, quality, and location.
Labour covers wages, salaries, allowances, overtime, insurance, and other benefits for skilled, semi-skilled, and unskilled workers. Labour productivity and availability can significantly influence the final cost.
Equipment includes excavators, cranes, concrete mixers, generators, scaffolding, and other machinery. Costs may arise from purchase or hire, fuel, maintenance, repairs, and equipment operators.
Every successful project begins with a well-planned cost; when resources are managed wisely, risks are controlled, and every investment is given purpose, a vision can become a lasting reality.
Indirect Costs: Indirect costs support construction activities but cannot easily be assigned to one specific task. They may include site offices, temporary facilities, utilities, security, communication, supervision, health and safety measures, transportation, and logistics. Although these costs may not become part of the finished building, they are essential for efficient project execution.
Professional and Consultancy Fees: Construction projects depend on professional expertise. Architects, engineers, quantity surveyors, project managers, environmental consultants, estate surveyors, and legal professionals provide services that contribute to proper planning, design, costing, compliance, quality assurance, and project control.
Land and Acquisition Costs: For development projects, the cost of acquiring and preparing land can be substantial. Expenses may include the purchase price, surveys, legal documentation, registration, compensation, and title processing. Location, accessibility, infrastructure, and development potential can greatly affect land value.
Regulatory and Approval Costs: Projects often require statutory approvals and permits before and during construction. These may include planning and building approvals, environmental assessments, inspections, utility connections, and other regulatory charges. Proper compliance helps prevent delays, penalties, and legal complications.
Contingency and Financing Costs: Because construction projects face uncertainties such as inflation, design changes, unforeseen ground conditions, and price fluctuations, a contingency allowance should be provided for unexpected expenditure.
Where external funding is involved, financing costs such as loan interest, bank charges, transaction fees, insurance, and financial advisory costs must also be considered.
Overheads and Profit: Contractors incur general business expenses such as office rent, administrative salaries, information technology, insurance, and management costs. These overheads are normally distributed across projects.
A profit margin is also included to compensate the contractor or developer for business risks and provide a reasonable return on investment. The appropriate margin depends on project complexity, competition, market conditions, and risk exposure.
Operation and Maintenance Costs: Project cost should not always end at construction completion. For long-term assets, consideration should be given to future repairs, servicing, replacements, utilities, and facility management. Evaluating these life-cycle costs can help stakeholders select solutions that offer better long-term value.
Key Insight
Effective project cost management requires more than calculating the price of materials and labour. Direct and indirect costs, professional fees, land acquisition, regulatory requirements, contingencies, financing, overheads, profit, and future maintenance all contribute to the true cost of a project.
A thorough understanding of these components enables stakeholders to develop realistic budgets, control expenditure, reduce financial risks, improve profitability, and make better investment decisions. Ultimately, accurate cost planning is one of the foundations of successful, sustainable, and financially responsible project delivery.